
Dear readers,
Today I bring a company that is not very well known by the investment community. I love the aviation sector due to its high barriers to entry and the tailwinds of the industry.
You might notice the name says “Corporación”, rather than corporation. It’s not a typo. Today we are analyzing airports in Argentina and Uruguay.
I already own private hangars in American airports through Sky Harbour, and the majority of the engines of commercial planes through GE (which is up +100% since posting the investment thesis a year ago), and Safran, acquired a few weeks ago.
It’s a really interesting sector and I think it’s worth reviewing this company to understand the economics of operating airports.
Snapshot
Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It doesn’t constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available
Please remember that nothing in this post is investment recommendation.
1. Investment summary
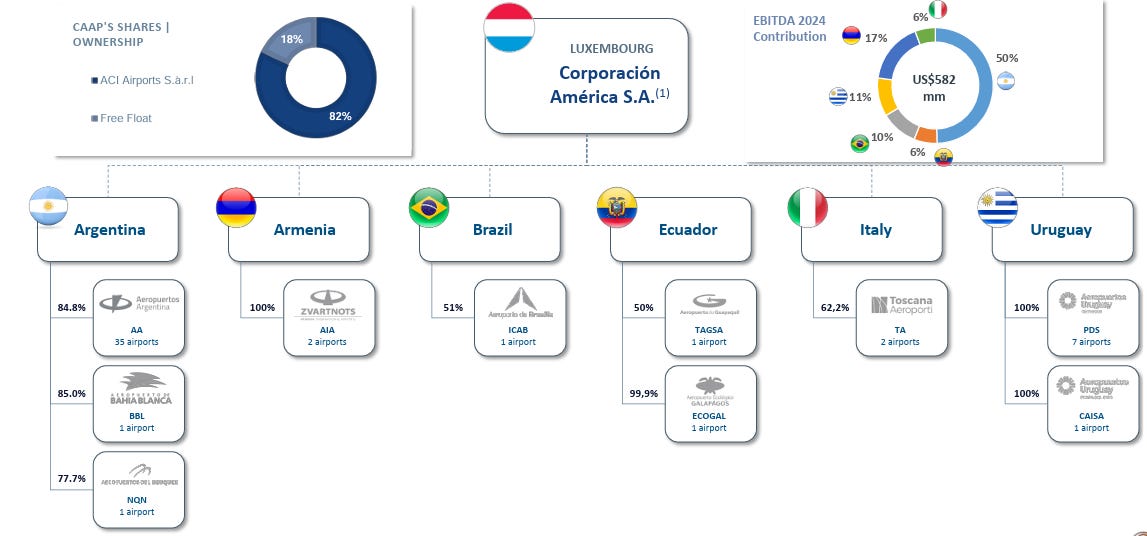
Corporación América Airports (CAAP) is one of the largest private airport operators in the world, running 52 airport concessions across six countries — Argentina, Brazil, Uruguay, Ecuador, Armenia and Italy — and serving 86.7 million passengers in 2025.
It is the listed vehicle of the Eurnekian family’s airport interests, controlled through A.C.I. Airports, and is the only pure-play, globally diversified airport concessionaire trading on a U.S. exchange.
The investment debate is unusually clean: a structurally attractive infrastructure business, growing double digits with the strongest balance sheet in its history, set against the market’s deep discount for its Argentine centre of gravity.
Argentina accounts for 50% of the EBITDA contribution. The remaining 50% in Ecuador, Uruguay, Italy, Brazil and Armenia
Company is headquartered in Luxembourg
The controlling family owns 18% of the shares
The bull case rests on four pillars:
First, concession economics: long-dated, quasi-monopoly airport contracts with regulated aeronautical tariffs and a fast-growing, higher-margin commercial layer (retail, duty-free, parking, advertising)
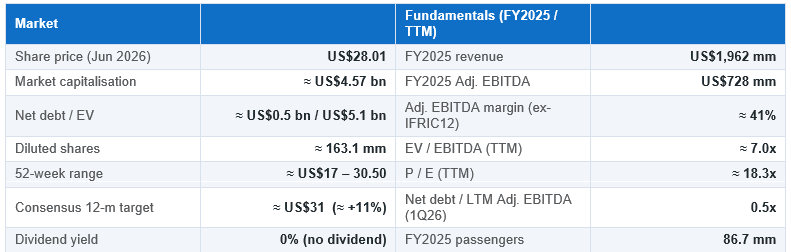
Second, operating leverage: FY2025 revenue ex-construction rose 8% while Adjusted EBITDA ex-IFRIC12 grew 15%, lifting that margin to roughly 41%, and 1Q26 carried the trend further with EBITDA ex-IFRIC up 26%
Third, a solid balance sheet — net debt fell to 0.5x LTM Adjusted EBITDA by 1Q26 with US$666 mm of cash, versus 2–3x typical for peers
Fourth, a credible growth pipeline: a 35-year Armenia extension to 2067 with a US$425 mm program, a Galápagos extension, and new awards.
The bear case is equally legible:
Argentina is the single largest driver of traffic and value, so currency, inflation and political risk dominate; IAS 29 hyperinflation accounting injects real distortion into reported numbers;
The assets are concessions (finite, renewable, occasionally subject to government buy-out rights) rather than owned freeholds;
The company pays no dividend; and
Control sits with a single family with related-party history. These are the reasons CAAP trades at roughly 7.0x EV/EBITDA against 9–13x for Mexican and European peers.
