I. Executive Summary
Dear readers,
Today I bring another high quality company that all you know, but I bet just a few know that it’s a publicly traded company: Lindt.
Chocoladefabriken Lindt & Sprüngli AG (Lindt), is a Swiss-headquartered premium chocolate manufacturer. You will certainly know this company as they are in all supermarkets, and probably, always the most expensive chocolate, driven by the quality of the product.
The Group operates a vertically integrated value chain across 12 production sites and reports under three geographic segments:
Europe (50% of revenue),
North America (37%), and
Rest of the World (13%)
The investment story is one of category leadership in premium and super-premium chocolate, with a portfolio of brands led by Lindt and Lindor (35% of revenue), Excellence (14%) and the seasonal Gold Bunny franchise (≈8%), complemented by US assets Ghirardelli and Russell Stover and heritage Italian/Austrian labels Caffarel, Hofbauer and Küfferle.
Lindt has compounded returns on invested capital from approximately 12% in 2016 to 23.1% in 2025 and has paid an increased dividend for 30 consecutive years.
With FY2025 revenue of CHF 5,920 million, EBIT of CHF 971 million (16.4% margin) and net income of CHF 738 million. At the actual prices, Lindt trades at an implied total market capitalization of CHF 22.0 billion across different share classes and an enterprise value of CHF 22.2 billion.
This translates to:
Forward EV/EBITDA of approximately 17.0x
P/E of approximately 30x on FY2025 figures.
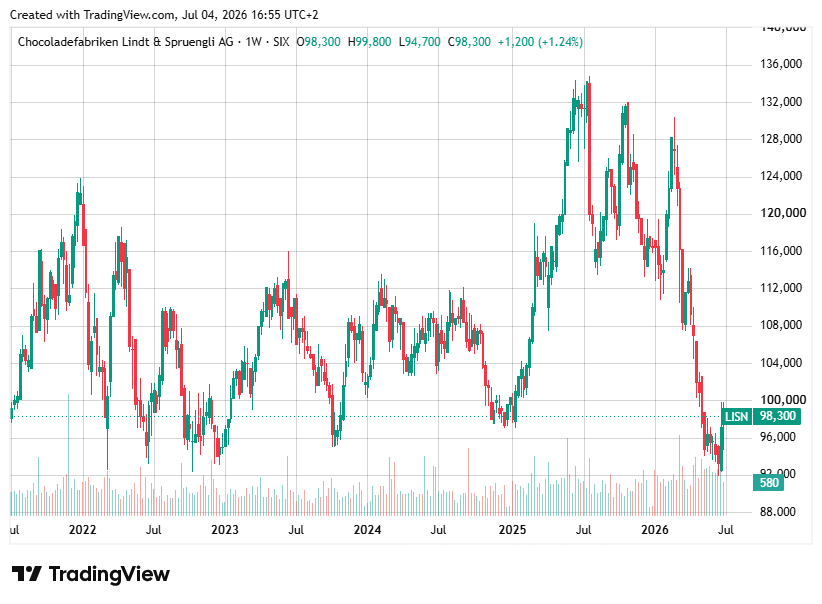
The 12-month consensus price target implies upside of +22.6% on the LISN and +10.4% on the LISP. The Group cut its 2026 organic growth guidance to 4–6% from a long-term 6–8% target in March 2026, citing volume-elasticity in response to double-digit price actions and US trade-policy frictions; shares fell more than 6% on the announcement.
The share price performance has been weak — mainly impacted by a reduced guidance for 2027 — and it’s time to see if this represents an interesting opportunity for the long-term.
Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It does not constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available information.