
Disclaimer. Please read full disclaimer at the end of the page before reading the report. This publication is only for information and entertainment purposes. It doesn’t constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available
Antin: 1H 2025 Results – Slow but Steady Progress
Antin reported its results for the first half of 2025 this week. In short: not much happened.
While we are still expecting more activity from Antin—particularly from the Flagship Fund—the company has only completed one acquisition under the NextGen strategy this semester.
The weakness of the USD has negatively impacted two planned exits from Fund III, but it could also present an opportunity to deploy capital at a more favorable exchange rate.
Management remains cautious but confirmed that fundraising for the Mid Cap strategy will begin next year, with Flagship fundraising to follow.
Overall, things are progressing slowly, but Antin remains a very solid business. Mid Cap and NextGen strategies appear largely de-risked (capital has been deployed, so now it’s about execution), while Flagship still requires more work before its next cycle.
The next fundraising cycle will begin in about a year. This will likely mark a new step-change for Antin. While this cycle was delayed due to challenging market conditions, the company’s strong balance sheet and consistent dividend (~6% annually) provide investors with some cushion.
Adding carried interest into the picture, future shareholder returns could be meaningfully higher than what we are seeing today.
Documents:
I. Assets Under Management (AUM)
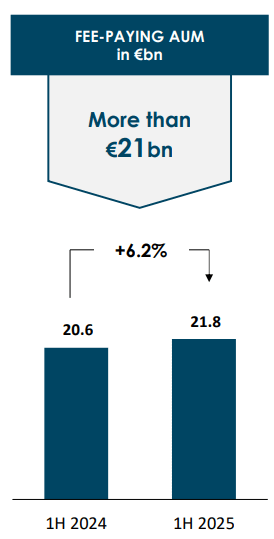
Fee-Payin AUM
No material changes during the semester—no exits, no new fundraising. This figure will dip slightly if Fund III is divested, before expanding again in the next fundraising cycle.
Assets Under Management
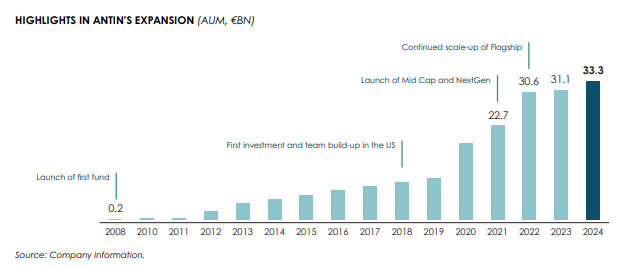
Stable at €33 billion.
Antin tends to grow in step-changes, every 4–5 years, as each fundraising cycle plays out. The company continues expanding its team and preparing for the next cycle. Zooming out, AUM has grown from €0.2 billion to €33 billion over the past 15 years—an impressive compounding story.
II. Transactions During the Semester
Only one acquisition this semester—a disappointing result given the market opportunity. Management needs to accelerate deployment.
Exits remain key, as they smooth the process of raising new funds.
Exit Pipeline
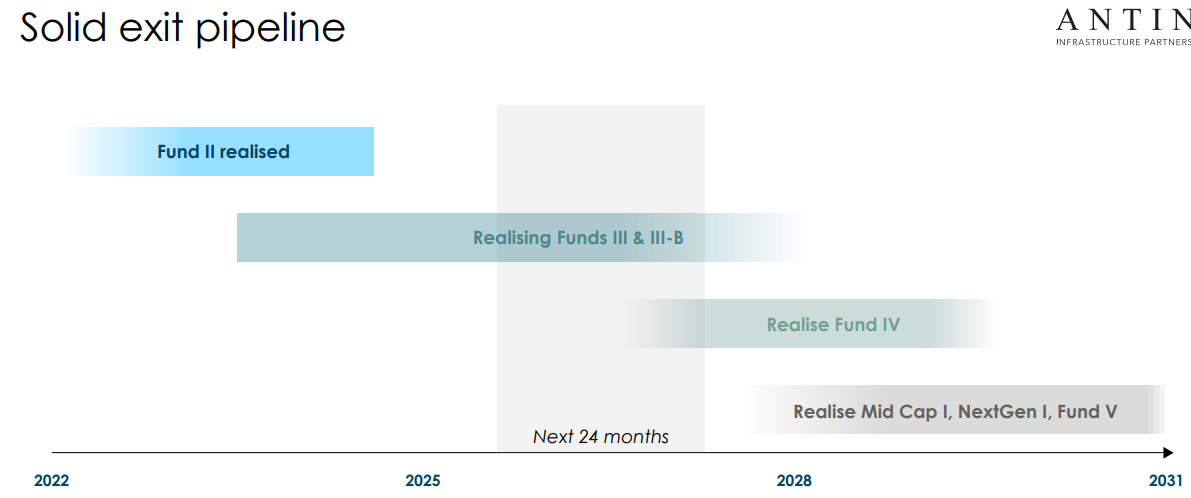
The company presented their plan, but they have faced delays on prior plans, so I won’t take it as granted:
Flagship Fund
No major updates. This is concerning, as Flagship is Antin’s core product. Of the €10.2 billion committed, only €3.0 billion has been invested. We are still within the investment period, and management is taking a disciplined approach (“better slow and good than fast and bad”).
The timing of these investments will ultimately determine when the next Flagship fund can be launched—Antin’s primary growth driver.
Management had initially expected two exits in 2025, but comments on the call suggest they may slip into 2026.
Flagship III Portfolio includes:
Solvtrans (freight and logistics)
elanta (fiber)
CityFibre — Just raised £2.3bn in new financing to fund the expansion of its nationwide full-fibre broadband network, support mergers and acquisitions to consolidate the alternative network (altnet) sector in the UK, and invest further in digital infrastructure and connecting more premises.
Firstlight (fiber)
idex (district energy)
Kisimul (special education)
Some of these companies are ready for exit, while others like CityFibre — which recently raised £2.3 bn for growth — remain in a growth phase.
Mid Cap
Management expects to announce two investments shortly. If they close, Mid Cap Fund I will be nearly fully invested—positioning Antin to launch fundraising for Mid Cap Fund II in 2026.
If they deliver these two acquisitions, Mid Cap Fund I will be on track to be fully invested soon. This will allow to start fundraising during the next year.
NextGen
The acquisition of Matawan was announced in September. It is a fast-growing smart mobility platform serving public transport networks across Europe and the US.
III. Fundraising Update
Management confirmed that they will raise funds for Mid Cap Fund II, and Flagship Fund V will follow.
“If we have the ambition of raising a bigger fund, a Mid Cap II larger than Mid Cap I, evidently, we'll need to get new money, as we say in our verbiage, and this means that the premarketing actually focuses precisely on new money and not existing money because people know us”
By order:
Management confirmed the sequence of upcoming funds:
Mid Cap Fund II – Fundraising expected to launch in 2H 2026.
Flagship Fund V – To follow in early 2027.
NextGen II – Likely after the above two, once current investments mature.
New Strategy - Will follow if they se enough apetite.
Launch of new strategy
This was announced during the start of the year, however it has not yet materialized, and it sounds like it won’t happen this year.
Company is testing the water to see if there is apetite, as they need to see enough interest to raise significant amount of funds (NextGen raised €1.2 bn).
“We have to wait for the proper time to go to market on a new strategy”
IV. Portfolio Update
The companies in the portfolio companies delivered solid growth during the last 12 months:
+10.4% revenue growth,
+19.1% EBITDA growth (not all organic).
The company has signed multiple add-on transaction at the portfolio companies. Some of the activity includes:
A new GBP 2.3 billion financing round for CityFibre.
Acquisition of 500 MW from Acciona Spain by Opdenergy
Several add-on transactions across the portfolio
An intense semester which is always very positive as this is how private equity firms create value.

“Things are going back to normal. Financing, as you know well, also are available”
V. Fund Updates
Flagship
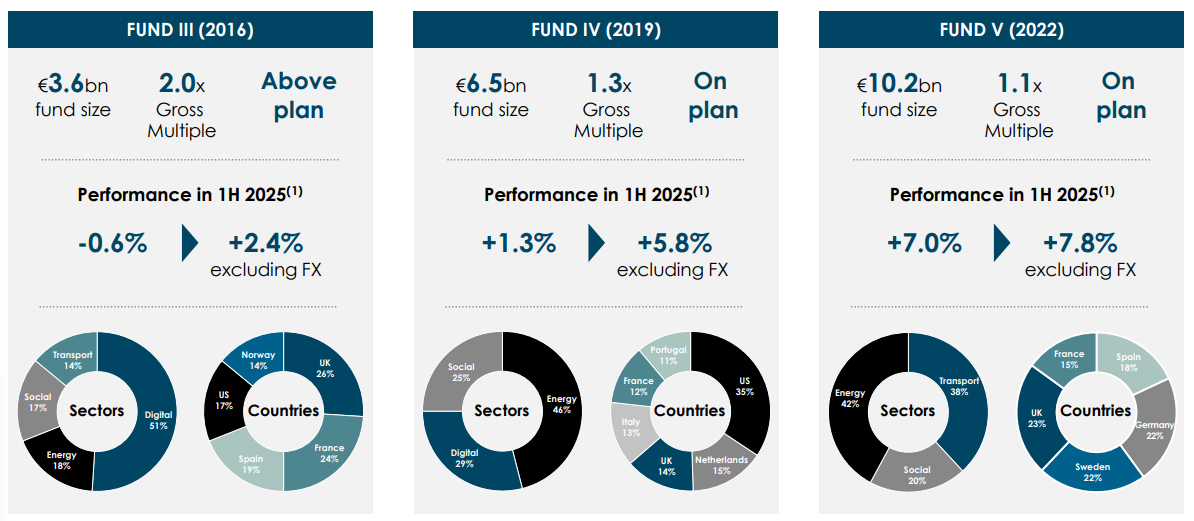
Flagship Fund III – Near full maturity; ready for divestment. Expected 2.0x gross multiple.
Flagship Fund IV – Some assets approaching maturity.
Flagship Fund V – Significant capital still needs to be deployed. There is still time, but at some point they will be more pressured if they don’t deploy some capital during the next quarters.
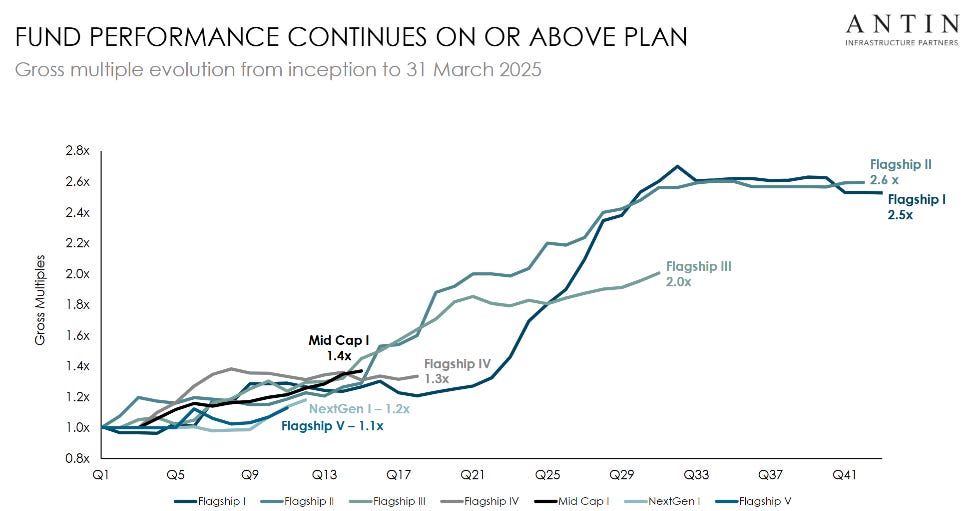
While Fund III’s performance is slightly below earlier funds (Flagship I & II delivered >2.5x), it is still attractive at 2.0x. Final returns will depend on successful exits.
Mid Cap
After the seventh investment, the fund is now more than 65% committed. They are in very advanced stages for acquiring two companies, which will make the fund nearly invested.
This strategy seems to be doing well and management is optimistic with raising funds again.
They raised €2.2bn in the first fund, so a second fund could start getting interesting it they reach €2.5-3.0 bn.
Performance stands at 1.4xm which seems higher than what other funds deliver during the first ~15 quarters (see image above with fund performances).
NexGen
Acquired one company this year called Matawan, a leading smart mobility platform serving over 330 transport networks across Europe and North America. The partnership aims to accelerate Matawan’s growth, expand its footprint, and support the transition to more sustainable, integrated public transport systems.
VI. Profitability and P&L
Nothing happened in terms of raising funds, but the company maintained its strong financial performance. Last year was affected by catch-up fees. Excluding catch-up, there is growth in all metrics.
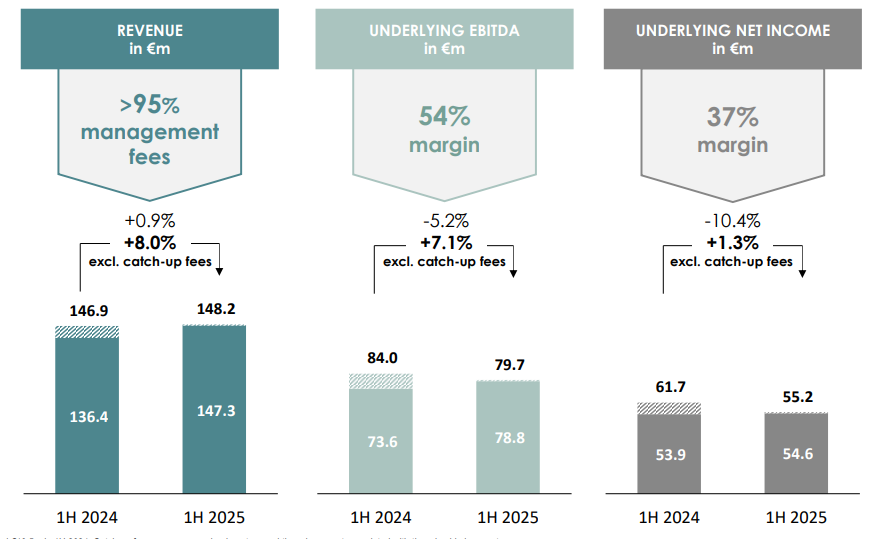
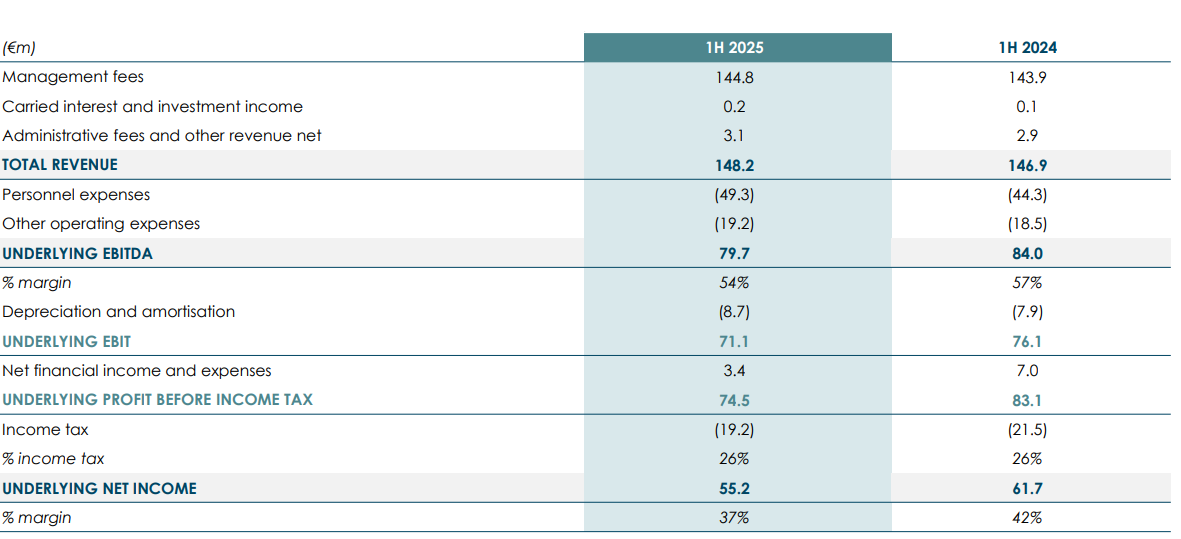
As seen in the P&L, revenue was stable during the semester, while margins compressed as the company keeps investing for growth (i.e., increasing its personnel and associated expenses).
On the balance sheet:
Cash decreased from €390m to €360m (partly affected by the distribution of dividend and negative impact from working capital). This cash more than covers capital committed to current funds and future dividend distributions.
No financial liabilities.
