Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It doesn’t constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available
Please remember that nothing in this post is investment recommendation
1. Executive Summary
Have you ever booked a hotel through Booking? Search for a flight on Kayak? Or maybe through Priceline? Ever used OpenTable? Agoda?
All these are brands owned by Booking Holdings, the world’s largest online travel intermediary.
We recently invested in this company due to its market positioning, long-term tailwinds and a reasonable valuation for a business like this.
Our investment thesis rests on five pillars:
First, Booking.com, the world’s largest online intermediary that facilitates more than $185bn of gross travel bookings. It’s 1.5x larger than Expedia, the second largest group.
Second, the tailwinds of the industry. Tourism is an industry benefiting from tailwinds driven by the expansion of middle classes, social media and the need to travel, new lifestyle based on experiences and the ease of travel.
Third, a capital-light business generating strong cash flows with significant growth ahead.
Fourth, capital allocation has been disciplined and shareholder-friendly, buying back huge amounts of stock, further increasing shareholder returns.
Fifth, a reasonable valuation: c.23x earnings and c.18x FCF for a business compounding FCF per share at double digits. We always say that valuation matters — here it works in our favor.
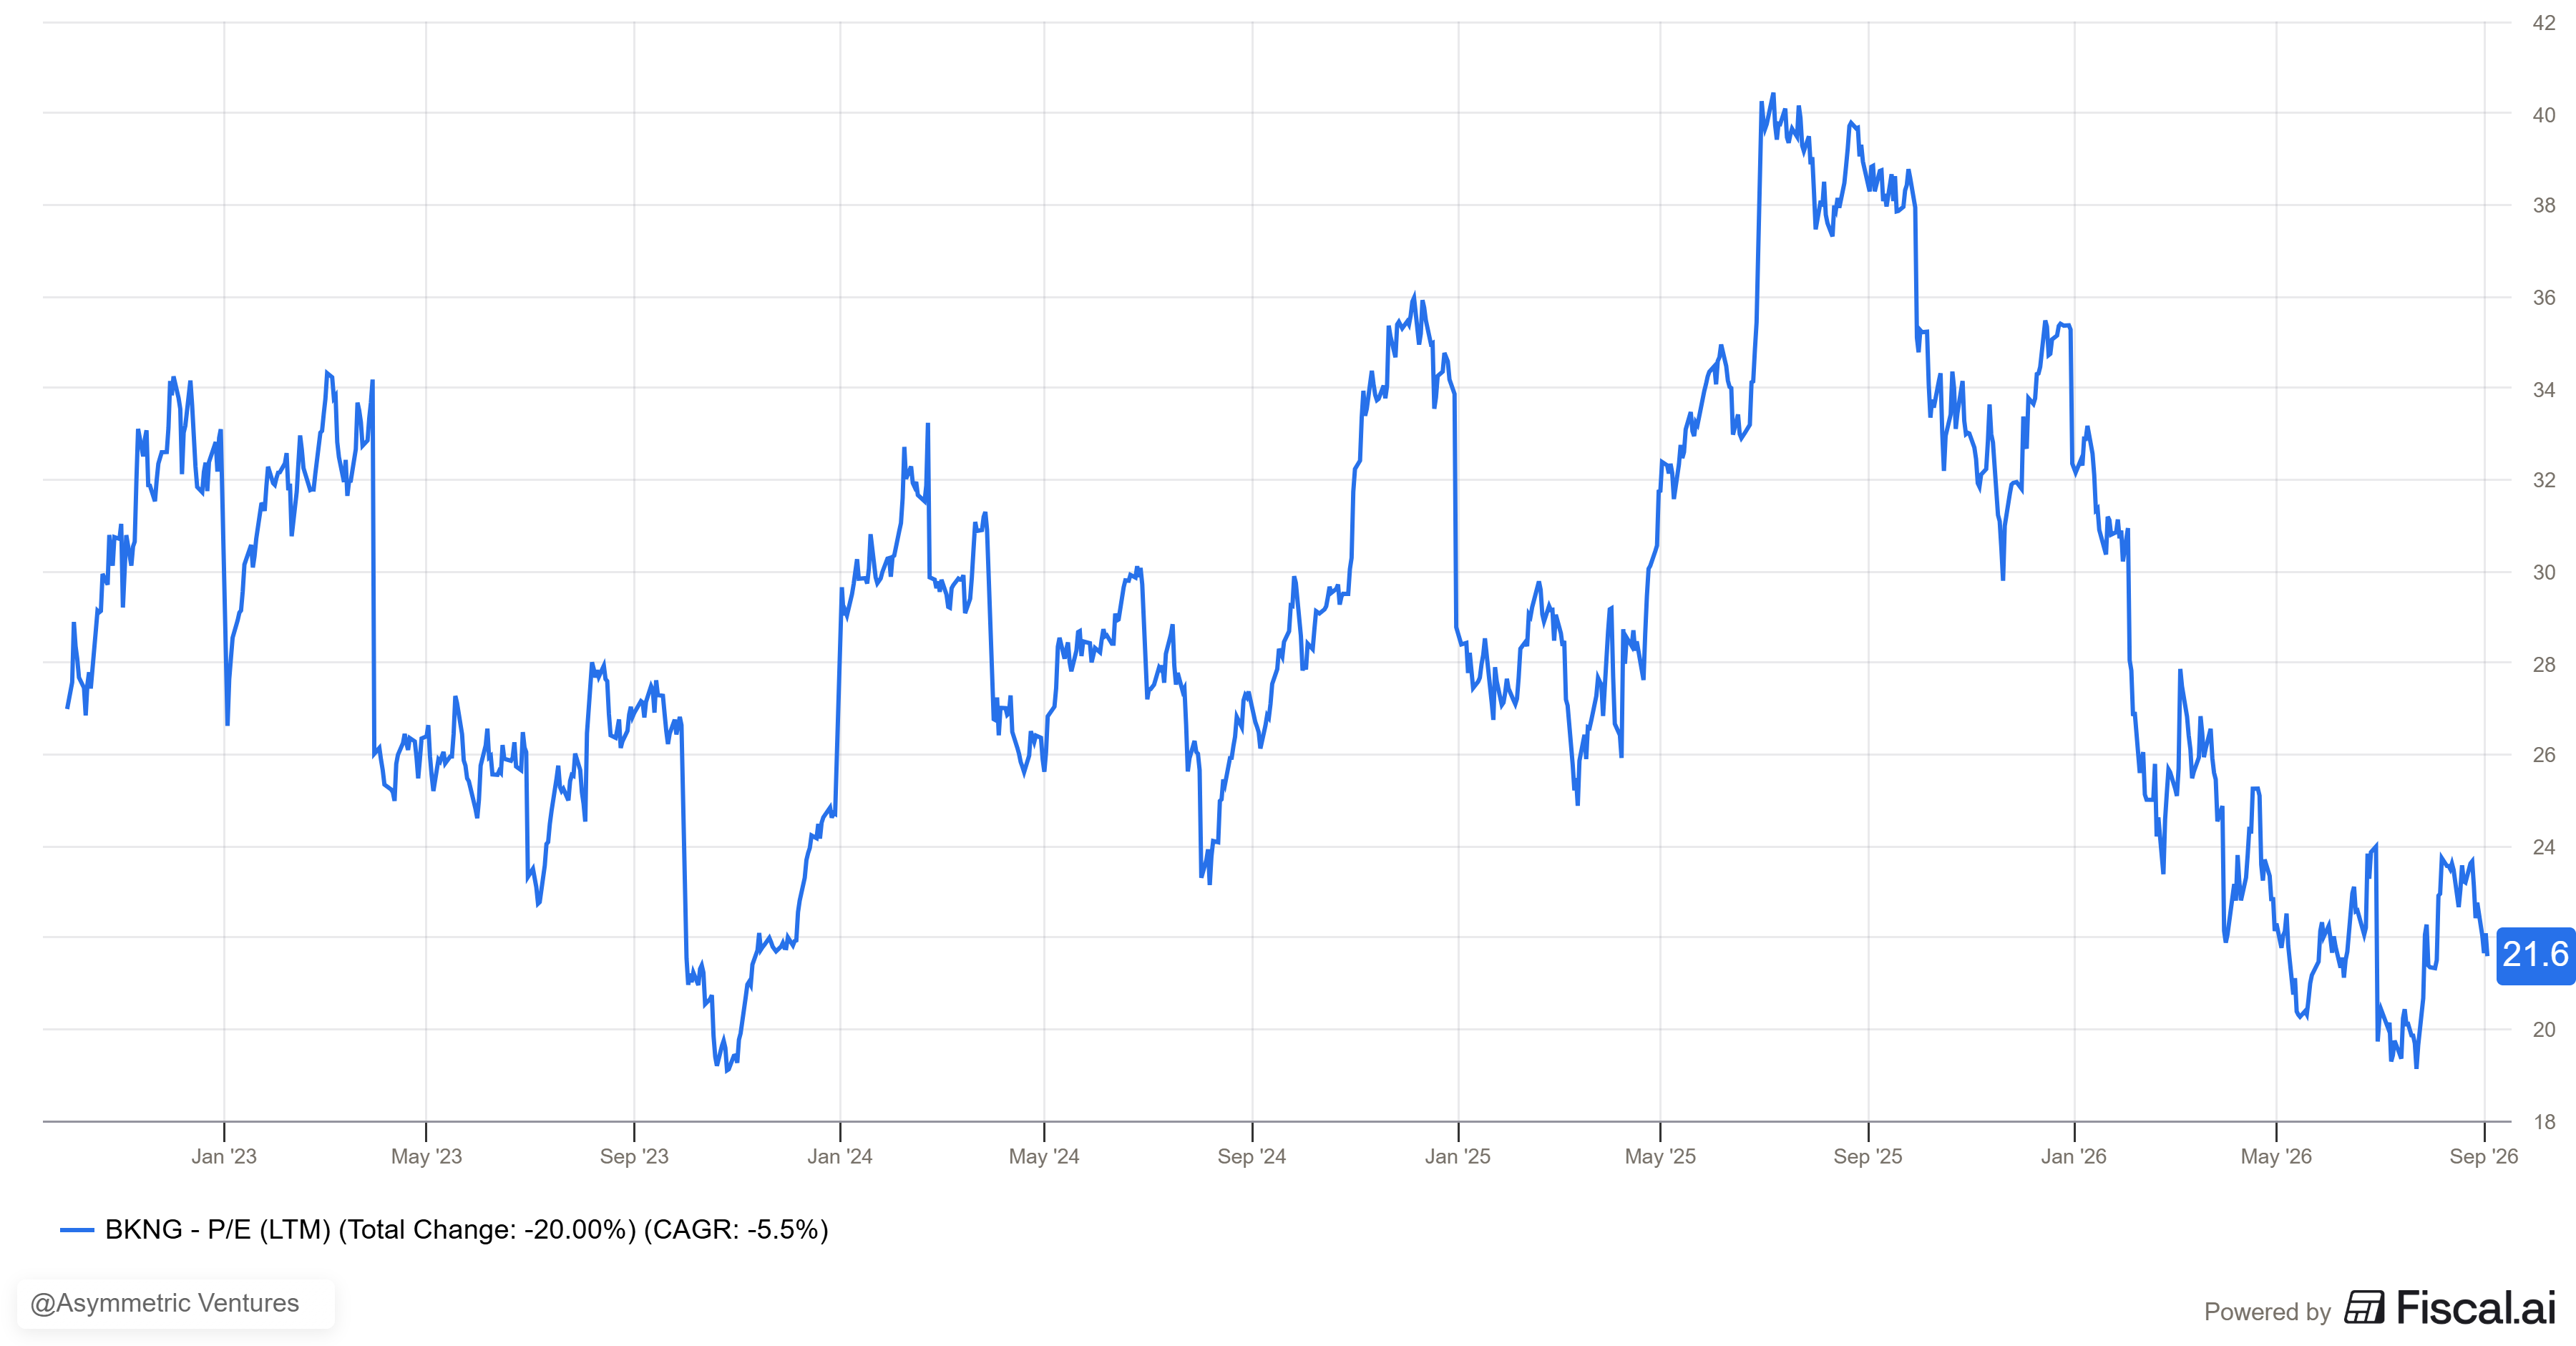
The threat of AI and LLMs disrupting platforms is also impacting Booking, which has seen its valuation compress: from trading above 30x to c.23x earnings today, a sharp de-rating over the last year, partly driven by the conflict in the middle east and its impact on tourism.
Risks to the investment thesis are real and well-disclosed:
The rise of Marriott and other major groups that are trying to bring customers to their own systems by offering lower prices and loyalty programs.
The rise of large generative-AI travel agents (Google Travel, ChatGPT plugins, Perplexity) could disintermediate the search-to-booking funnel that Booking has so effectively monetized.
💬 Our view: Booking Holdings is one of the highest-quality compounders in the global consumer internet space. The combination of category leadership, asset-light economics, global geographic diversification and aggressive return of capital to shareholders is rare.
The business has been performing very well during the last years. However, the rise of AI has increased concerns over the long-term sustainability of the business — a repeating pattern across many other industries.
But, as we will see, LLMs are unlikely to disrupt Booking’s business and increasing AI capacities can only improve the platform, becoming even more relevant.
Several quarters ago investors were willing to pay above 30x, with a median P/E of 28x over the last 4 years. Today, business keeps delivering good results, but valuation has been significantly reduced.
We believe this can represent an interesting opportunity, so we have been buying shares and reviewing the company in depth.