
Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It doesn’t constitute financial advice.
Please remember that nothing in this post is investment recommendation.

Index:
I. Introduction
II. Headline KPIs
III. Financial details
IV. Accommodation, regions and verticals
V. The FTC matter
VI. CEO prepared remarks: AI and the platform
VII. Call themes (Q&A)
VIII. Guidance
IX. Capital allocation and balance sheet
X. Recent news and market reaction
XI. Competitive and industry context
XII. Model update and valuation
XIII. Conclusions
I. Introduction
Booking Holdings reported third-quarter 2026 results on November 3rd, after the market close.
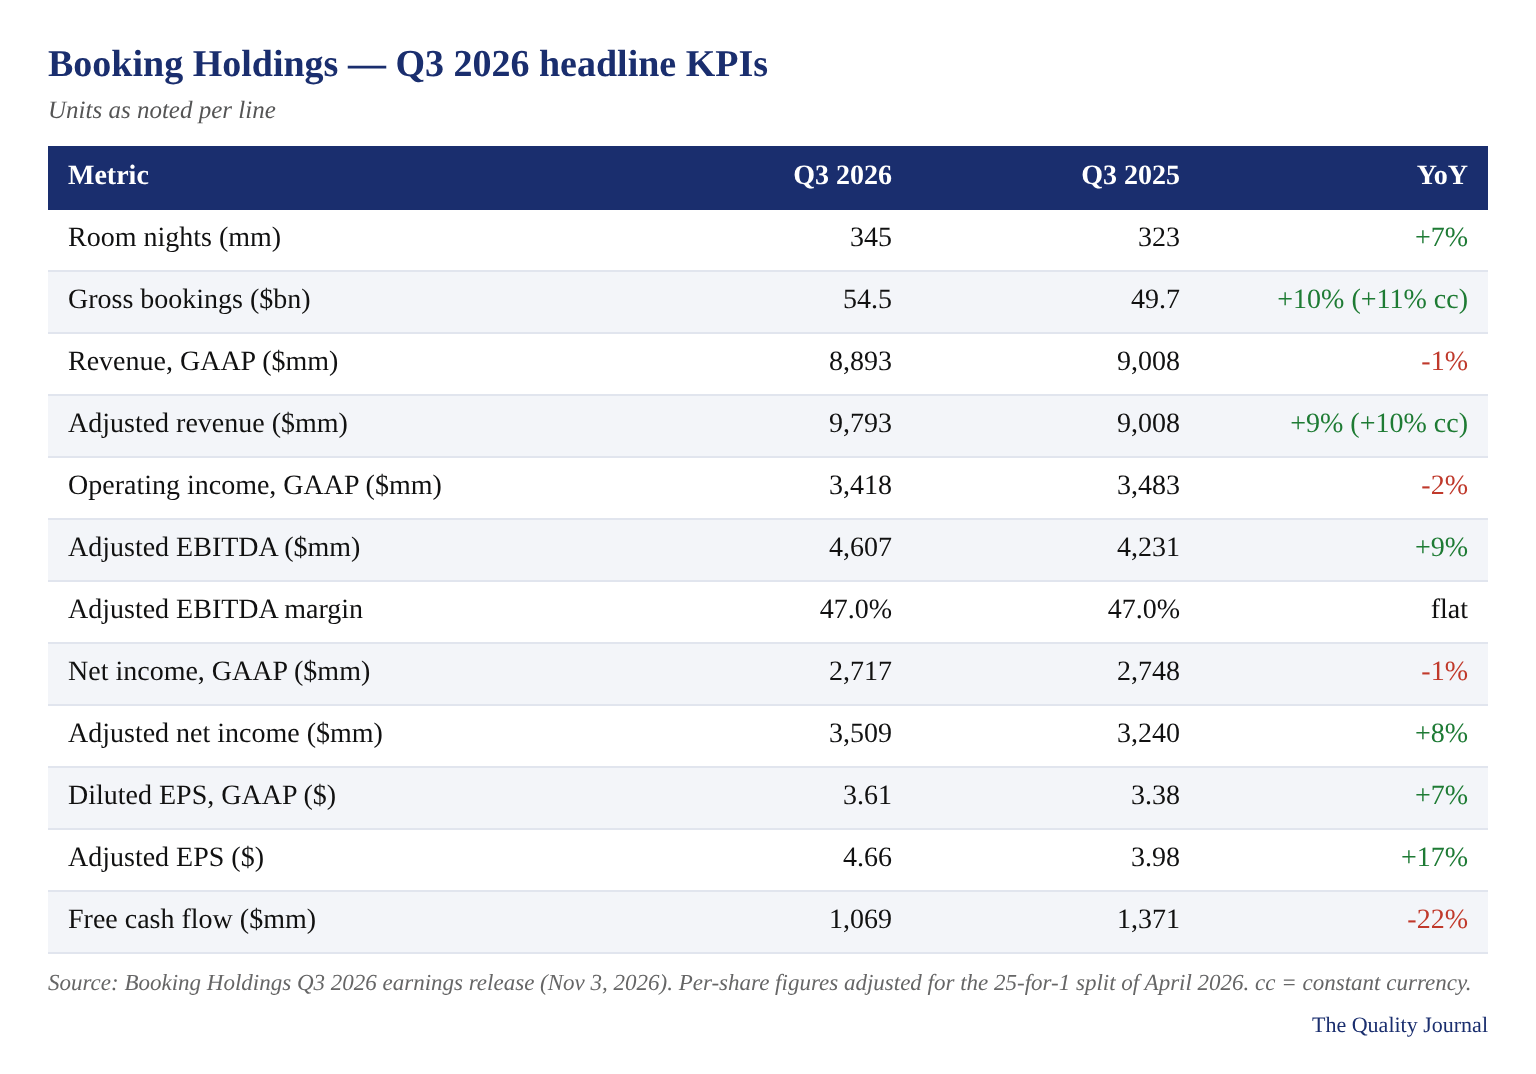
Room nights, gross bookings, adjusted revenue and adjusted EBITDA all came in above the high end of the guidance management gave in August (room nights +3% to +5%; gross bookings, revenue and adjusted EBITDA +4% to +6%).
Three topics dominated the release and the call with the analysts that we will review deeper in the analysis:
Room night growth re-accelerated to +7% (from +5% in Q2), with international travel originating from Europe and Asia improving while domestic travel stayed healthy.
A $1.0 billion charge related to an FTC matter involving Priceline and a B2B affiliate partner: a $900 million reduction in revenue plus a $100 million loss accrual. GAAP revenue therefore fell 1%, while adjusted revenue (which excludes the charge) grew 9%.
A soft fourth-quarter outlook: room nights +1% to +3% and adjusted EBITDA about flat, reflecting a late-September moderation in international demand, Middle East disruption and localized unrest in some European cities in October.
Overall, solid results as the company keeps delivering.
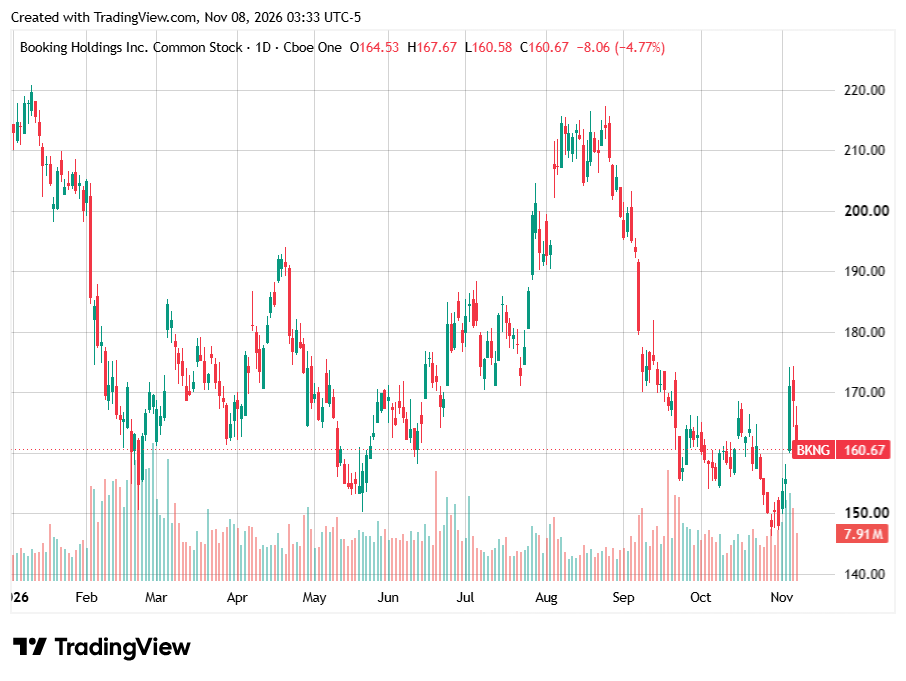
The shares closed at $157.26 on November 3rd ahead of the release and were roughly 27% lower year-to-date, near a 52-week low of $146.28. After an initial after-hours dip, the stock traded about 10% higher on November 4th, at around $171, and loosing all again on the “crash” of last Friday.
II. Headline KPIs
Booking kept growing volumes ahead of guidance, while earnings per share continued to benefit from a 7.5% lower average share count. The company delivered +10% revenue growth, in line with the long-term estimate, and repurchased around 1.5% of total shares.
Against consensus, Booking beat major metrics:
Adjusted EPS of $4.66 compared with estimates of roughly $4.43–$4.50, and
Adjusted revenue of $9.79 billion compared with a revenue consensus of about $9.54 billion.
Because consensus was built before the FTC charge, the GAAP revenue figure of $8.89 billion screened as a ~7% miss in automated headlines; on a like-for-like basis the top line came in ahead.
