
Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It doesn’t constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available
Please remember that nothing in this post is investment recommendation.
Summary
At the start of the month, WOSG published the results of the first half of 2026. The first half of the year confirmed what we were discussing during the FY 2025 results: the sector is recovering.
Step-by-step the company is regaining profitability and increasing the returns and cash generation.
A very solid semester driven by high growth in the US and stable market in the UK. Share price has recovered to nearly ~£5 per share. However, the share price is still below last year’s closing price of ~£6.
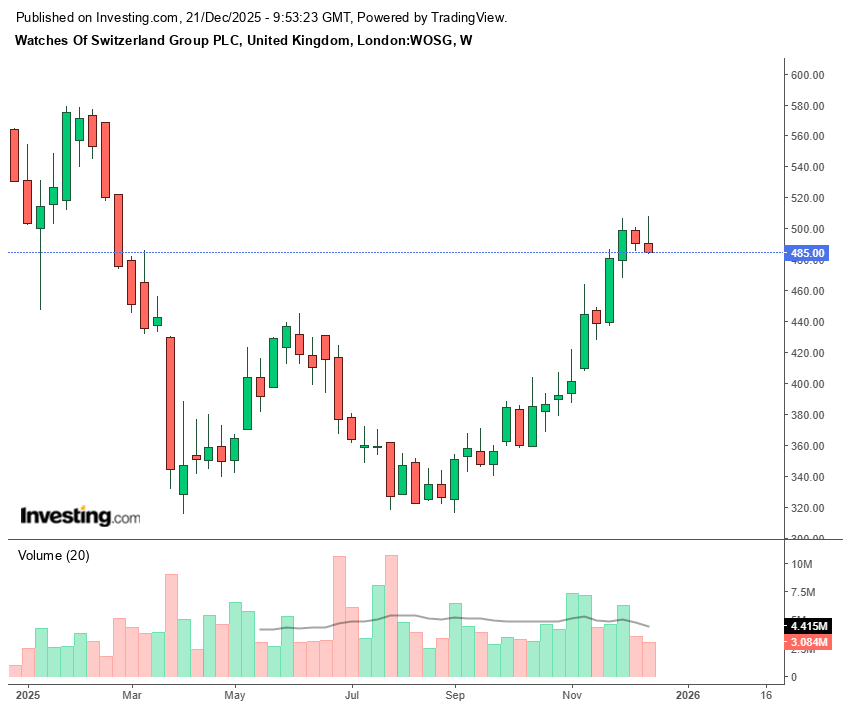
Share price has increased by 50% since reaching minimums of the year and the company is gaining strong momentum. After a long journey through the desert, the investment is returning 16%, implying an IRR of around 8% since my first investment in February 2024 which is not extraordinary, but we are now back in the positive territory.
In my humble opinion, the stock has room to continue growing due to the following factors (this is not a buy recommendation):
There is growth in both regions and margin recovery.
Cash flow generation increased by 60% compared to last semester, confirming the solid metrics.
The US and Switzerland reached an agreement to set tariffs at 15%. No more pressure from tariffs for the next quarters.
US Dollar has stabilized in the last months.
Going forward, f I was the management I will do two things:
Reinstate a share buyback of at least £30m (modest impact, but balance sheet is healthy and cash flow generation is going to be strong this year)
Consider a listing in the US to gain liquidity and attraction from US investors. The US is now the largest revenue contributor, with plenty of room to grow in the future. WOSG needs to trade in this market
