
Watches of Switzerland Group FY26: Reading the Year — Results and Strategy Deep Dive
Disclaimer. Please read full disclaimer at the end of the page before reading the article. This publication is only for information and entertainment purposes. It does not constitute financial advice.
The information provided in this blog is for informational purposes only and should not be considered as financial, investment, or professional advice. The valuations and analyses presented here are based on publicly available information.
Please remember that nothing in this post is investment recommendation.
Index:
Introduction
FY26 at a glance
United States: now the largest market
United Kingdom: fewer doors, more revenue
Group financials: P&L, cash flow and returns
Analyst Q&A: main themes from the results call
Strategy Deep Dive
FY27 guidance
Recent news and industry context
Valuation snapshot
Conclusions
I. Introduction
Watches of Switzerland Group reported its fiscal year 2026 results (53 weeks ended 3 May 2026) on 14 July 2026, and followed the morning results call with an afternoon Strategy Deep Dive — a c.100-slide capital markets presentation covering every pillar of the growth plan, with dedicated sections from the CEO, the Deputy CEO (US), the UK President, Hodinkee founder Ben Clymer, Deutsch & Deutsch President Tad Deutsch, and the CFO. This note covers both events, the analyst Q&A, and what our financial model implies about the underlying trends.
CEO Brian Duffy framed FY26 as “a year of strong execution against what was a complex and changeable operating backdrop” — a backdrop that included US tariffs, sharply higher gold prices, brand margin changes and ongoing consumer pressure in the UK. Against that, the group delivered a record year: sales of £1.828bn, up 13% in constant currency, with an improving trend through the year (H1 +10%, H2 +17%).
The structural milestone of the year: the US surpassed the UK to become the group’s largest market by both revenue and profits, reaching 51% of group revenue and 62% of adjusted EBIT (including Roberto Coin wholesale). Management noted the group remains 95% domestic-driven, with very little international/tourist business since VAT-free shopping was removed in the UK post-Brexit in 2021.
Duffy closed the call on a confident note: “2026 was clearly a good year for us in terms of sales growth and in terms of developing our infrastructure and our portfolio of our brands and stores… 2027, as we’ve been discussing, has started well, allows us to kind of confidently confirm our guidance.”

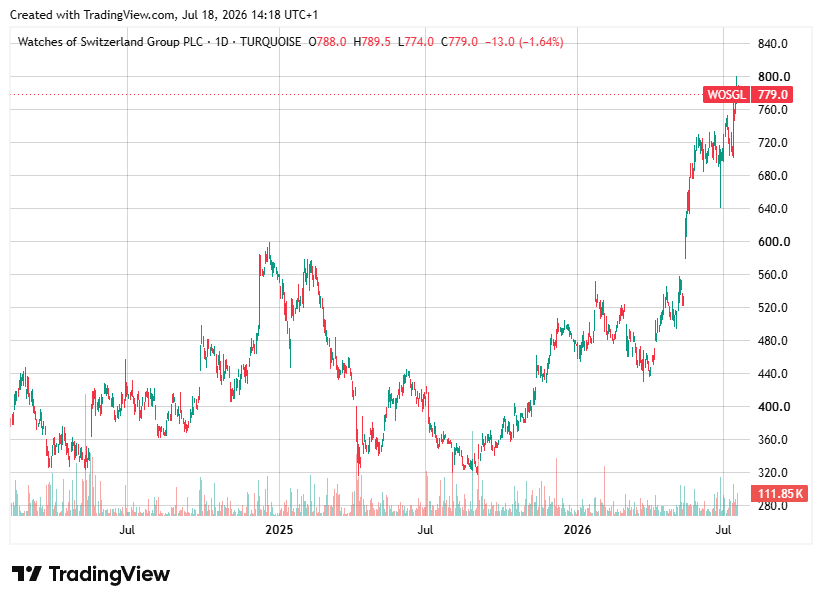
Over the last 2 years, I was looking like a fool by owning a Rolex retailer that “was going to disappear”. YTD, the stock is up +68%, and nearly +100% since we acquire the stock in March 2024.
A potential takeover?
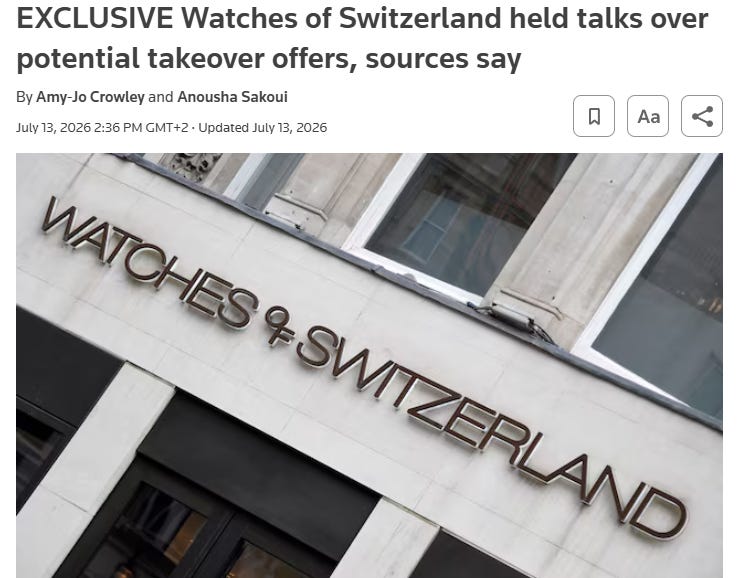
An important factor currently affecting the share price are recent press articles reporting that WOSG management held talks over potential takeover offers to take the company private.
Full press article: https://www.reuters.com/business/finance/watches-switzerland-held-talks-over-potential-takeover-offers-sources-say-2026-07-13/
There are several important conclusions from this article:
Private equity firms are looking at the company. This signals that the company remains undervalued, that cash flows are perceived as stable (to be able to leverage the buyout), and, there is still growth potential.
One of the sources said the company was seeking an offer of significantly more than £7.50 per share (the stock currently trades at £7.8 per share, so any offer IMHO should be significantly higher).
II. FY26 at a glance
The headline KPIs (constant currency unless noted; FY26 was a 53-week year):
Group revenue £1,828m, +13% constant currency (+11% reported); H2 accelerated to +17% vs +10% in H1
US revenue £927m, +24% (H2 +27%); US retail +25%; the US is now 51% of group revenue and 62% of adjusted EBIT
UK & Europe revenue £901m, +4% (+5% for the UK excluding the closed European showrooms)
Adjusted EBITDA £202m, +5%; margin 11.1% (-50bps)
Adjusted EBIT £155m, +6% constant currency (+3% reported); margin 8.5%, -60bps
Statutory PBT £133m, +76%; adjusted PBT £143m, +5%
Adjusted EPS 45.2p, +9% (+3.6p); effective tax rate 26.7% (-110bps, helped by a one-off Roberto Coin tax credit)
Free cash flow £162m with 80% conversion (FY25: £98m, 51%); net debt reduced to £57m (0.3x adjusted EBITDA)
ROCE 18.0% (FY25: 19.0%)
Growth pillars: pre-owned +22%, ecommerce +21%, Roberto Coin +20%; Mayors Roberto Coin shop-in-shop sales more than doubled
£66m of expansionary capex across 13 major projects; £39m spent on acquisitions (Deutsch & Deutsch plus the final Roberto Coin payment); £14m of buybacks in the year
Revenue CAGR FY15–FY26 stands at 15.5%, with adjusted EBIT compounding at 29.5% over the same period — a track record management leaned on heavily in the afternoon strategy presentation.
